Equipment hire: organise bookings, deposits and returns
Equipment sitting in the warehouse is not automatically available to hire tomorrow. It may already be booked, awaiting cleaning or out of service. Businesses renting equipment for a fee therefore need a process for time periods and condition alongside ordinary stock quantities. Rental charges and refundable security deposits must also remain separate.
- Bahram Davoodi
Equipment sitting in the warehouse is not automatically available to hire tomorrow. It may already be booked, awaiting cleaning or out of service. Businesses renting equipment for a fee therefore need a process for time periods and condition alongside ordinary stock quantities. Rental charges and refundable security deposits must also remain separate.
Availability is more than a quantity
Decide what customers actually book: a particular unit or any one of several equivalent units. This affects handover, replacements and returns. A general item count is insufficient when customers expect a particular accessory set or performance class.
Plan collection, agreed return and a realistic inspection or cleaning buffer. Equipment due back at 2pm is not necessarily ready for use again at 2pm. Consider late returns and maintenance before confirming the next booking.
What belongs in the handover record?
Item | Practical evidence |
|---|---|
Equipment | Clear description and unit number where relevant |
Period | Collection, return and agreed extension |
Accessories | Complete list, such as cable, attachments or charger |
Condition | Existing damage and functional check |
Money | Separate hire charge, payments and security deposit |
Responsibility | Contact and process for faults or delays |
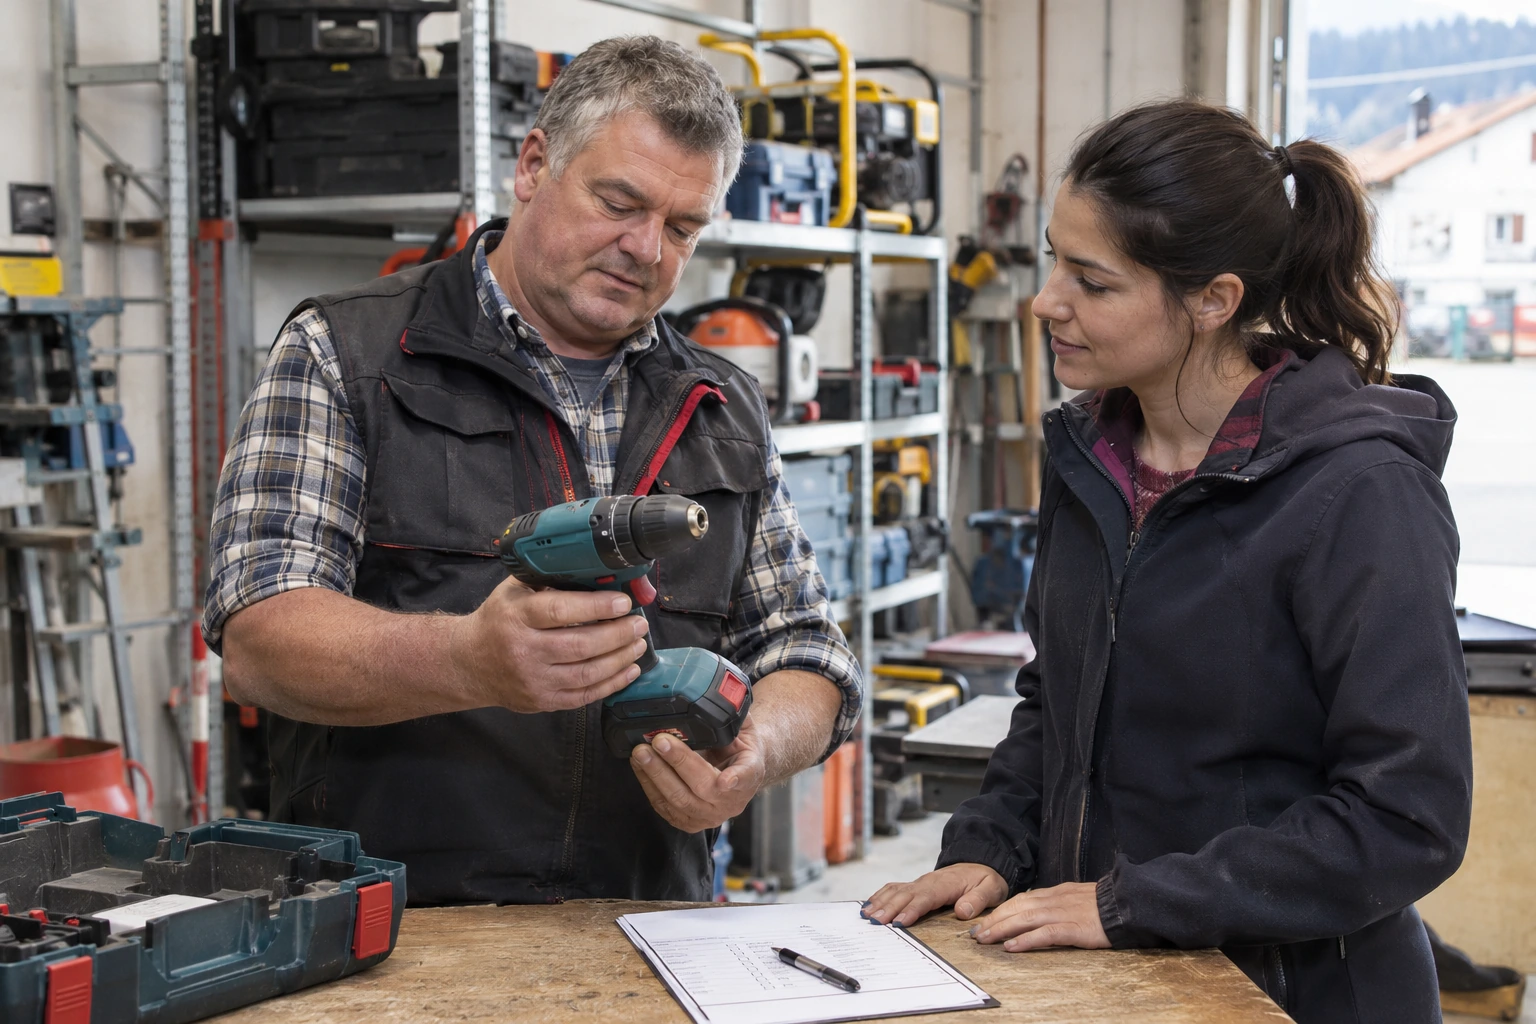
Explain safe use and supply the required instructions. Record who takes possession and which documents accompany the equipment. A signed record is particularly useful when it describes the actual condition rather than merely ticking “all fine”.
Security deposits are not extra rental income
Explain the amount, payment method, purpose and return of the deposit clearly. A purely refundable security deposit must not be treated internally as additional earned rental charges. Have its specific accounting and tax treatment checked, including any later application of the deposit.
With cards, charging money and merely reserving an amount are different operations. The documentation on authorisation and capture illustrates the distinction using one payment provider. Available procedures and validity periods depend on the provider and payment method. This does not establish that every terminal or your Lonio setup supports the same deposit function.
Example: returned does not mean available
A fictional hire business rents out a floor cleaner for €25 and takes a further €100 refundable deposit. The €125 received is not all rental income. On return, staff check the machine, cable and attachment. Cleaning follows before the next hire begins.
If an attachment is missing, record the case and resolve it under the contract and applicable law. Do not simply book the whole deposit as damage income without review. Normal wear and attributable damage are not the same thing either.
The Austrian duty to return rented property is addressed, among other provisions, in Section 1109 ABGB. Any particular claim must be assessed separately. A condition report helps that assessment but does not automatically determine the entitlement.
Check the process with Lonio
Lonio describes reservations, inventory and contracts and documents. Use a concrete test case to check how the period, resource, document and payment connect. Automatic management of every serial-numbered rental asset, card preauthorisation and deposit refunds are not promised here.
Before launch, also test an extension, late return and unavailable unit. Staff need a visible status and responsible person for each case. This helps prevent a telephone promise from accidentally becoming a double booking.
Frequently asked questions
Is ordinary stock management enough for hire?
Not always. Time periods, reservations, condition and downtime also matter.
Is a deposit revenue when received?
A purely refundable security deposit is not additional earned rent. Confirm its specific accounting treatment and subsequent use separately.
Can the next booking start immediately after return?
Only if inspection and preparation are realistically possible. Plan a suitable buffer instead of assuming instant availability.